Fire and Smoke Damage
An investment in knowledge pays the best interest
-Benjamin Franklin
Fire and Smoke damage
A fire can change everything in a matter of minutes. Beyond the visible damage, homeowners are often left facing smoke and soot contamination, water damage from firefighting efforts, temporary housing concerns, damaged personal belongings, and the uncertainty of navigating a complex insurance claim. It can be overwhelming—but you don't have to figure it out alone.
Whether your loss involved a kitchen fire, electrical fire, lightning strike, wildfire, or another unexpected event, this page is designed to help you understand what comes next. You'll learn how fire and smoke damage can affect your property, what homeowners insurance commonly covers, the steps involved in the claims process, common challenges to avoid, and practical guidance to help protect your interests every step of the way.
At VIP Adjusting, we believe that informed policyholders make better decisions. That's why we've created this resource to educate first and advocate second. Take your time, explore the information below, and if you have questions about your specific situation, we're here to provide a complimentary inspection, policy review, claim evaluation, and consultation—so you can move forward with confidence.
Our Complimentary Review
Free Policy Review
Free Property Inspection
Free Claim Evaluation
No Obligation Consultation
An Education on Insurance Claims
What You Will Learn on This Page
-
When a fire is extinguished and the smoke settles, homeowners and business owners are left in a lurch on how to pick up the pieces immediately afterwards. We can help guide you through that burden with a clear and concise plan to put the pieces back together.
-
Insurance policies are confusing because they are written in legal jargon by corporate attorneys. We break it down to layman terms that the average person can readily understand. Many homeowners are surprised to learn that a fire claim often involves much more than burned materials. We'll explain the types of damage that are commonly covered under many homeowners insurance policies, including structural damage, smoke, soot, firefighting water damage, debris removal, and additional living expenses. Because every policy is different, we'll also discuss why coverage ultimately depends on your policy language and the specific facts of your loss.
-
Each one of these perils cause their own specific damage and they are all connected to one single loss. It’s imperative to understand what and how each of these cause damage even if invisible to the eye. We’ll explain the importance of understanding some of the science behind each so you have a clear understanding of what’s on the table for coverage. Fire affects a home in many different ways, and not all damage is immediately visible. Discover how heat, smoke, soot, and water can impact your home's structure, contents, and indoor environment long after the flames have been extinguished, and why understanding each type of damage is essential to a complete restoration.
-
Understanding the claims process can reduce uncertainty and help you make informed decisions. We'll walk you through each stage—from emergency mitigation and the insurance inspection to documentation, estimating, negotiations, and settlement—so you know what to expect every step of the way.
-
Even well-intentioned decisions can unintentionally create challenges during an insurance claim. Learn about the most common mistakes homeowners make after a fire and how proper documentation, communication, and planning can help protect your interests throughout the recovery process.
-
Thorough documentation is one of the most important aspects of a successful insurance claim. We'll show you practical ways to photograph damage, organize receipts, inventory personal belongings, preserve important evidence, and create records that support a complete and accurate claim.
-
We've compiled answers to many of the questions homeowners ask after experiencing a fire or smoke loss. Whether you're wondering about smoke odors, temporary housing, damaged belongings, claim timelines, or insurance coverage, our FAQ section provides straightforward, educational answers to help you navigate the recovery process with confidence.
A Welcome Video on Fire and Smoke Damage Claims
A fire insurance claim can involve much more than the property directly damaged by flames. Smoke, soot, water used during firefighting, damaged contents, hidden contamination, temporary repairs, mitigation, and rebuilding may all become part of the recovery process.
This video introduces our complete Fire & Smoke Damage Insurance Claim Guide and explains how to use the resources on this page to better understand the road ahead. You don't need to learn everything at once. Start here, educate yourself about the process, and work through the sections below at your own pace.
Whether you work with VIP Adjusting or not, we fully encourage any member of the public to educate themselves to the fullest on Property Damage Insurance claims.
Watch this video from VIP Adjusting on how to start.
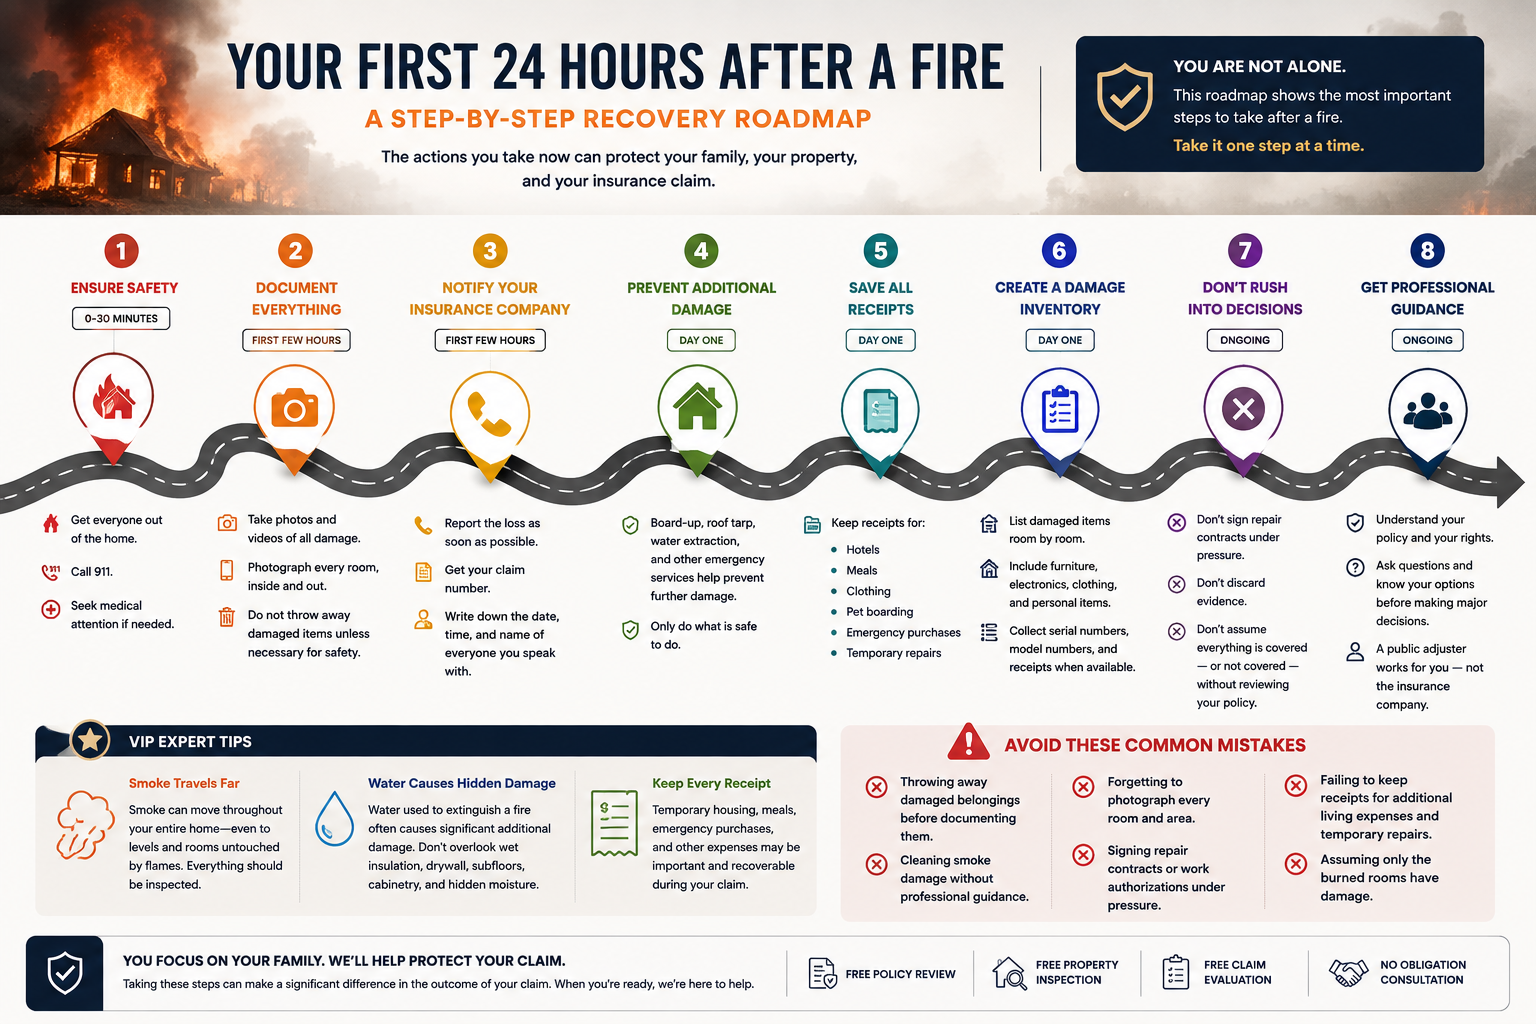
The first 24 hours after a fire can be overwhelming, and the decisions made during this period can affect both your recovery and your property insurance claim. In this video, VIP Adjusting explains important steps to consider immediately after a fire, including documenting fire, smoke, soot and water damage, notifying your insurance company, protecting the property from further damage, preserving receipts and expenses, documenting damaged contents, and avoiding rushed decisions or contracts. Learn how to approach the critical first 24 hours with a better understanding of the fire damage insurance claim process.
Your First 24-Hour Checklist
✓ Make sure everyone is safe and seek medical attention when necessary
✓ Photograph and video the property extensively
✓ Notify your insurance company of the loss
✓ Take reasonable steps to prevent additional damage
✓ Save receipts and document loss-related expenses
✓ Begin an inventory of damaged contents and property
✓ Avoid rushing into contracts or major decisions
✓ Identify qualified professionals who may be needed
The First 24 Hours After a Fire
The first 24 hours after a fire can be overwhelming, but the decisions made during this period can have a significant impact on both your recovery and your insurance claim. Once everyone is safe and any necessary medical attention has been addressed, your focus should shift to documenting the damage, notifying your insurance company, protecting the property from further damage, and preserving records of your expenses.
Take extensive photographs and video before cleanup or repairs alter the condition of the property. Secure openings in the roof, walls, windows or doors when it is safe to do so, and keep receipts for emergency repairs, temporary lodging, meals and other expenses related to the loss. Creating an early inventory of damaged property can also provide valuable documentation as the claim progresses.
Most importantly, don't allow the urgency of the situation to pressure you into making major decisions before you understand your options. A fire can bring contractors, restoration companies and other professionals into your life very quickly. Take the time to understand the process, evaluate the professionals you may need, and make informed decisions about your property and your claim.
Watch the video for the steps you should consider during the critical first 24 hours following a fire.
-
The first 24 hours after a house fire can be overwhelming. In a matter of minutes, your home, belongings, normal routine, and sense of security can all be disrupted. Once the fire department leaves, homeowners are often standing in front of a damaged property wondering a very simple question:
What am I supposed to do now?
The answer is not to solve everything at once.
Your immediate priorities are protecting people, securing the property, preventing additional damage when reasonably possible, notifying your insurance company, preserving evidence, documenting your loss, and keeping good records. There will be time later to address estimates, repairs, contents restoration, insurance payments, and the many other issues that can arise during a fire insurance claim.
The actions you take during these first hours and days, however, can have a significant impact on both the recovery of your property and the documentation of your insurance claim.
Every fire and every insurance policy is different, so the following should be viewed as general educational guidance rather than instructions for every situation. When safety officials, your insurance policy, or the specific circumstances of your loss require something different, those considerations should take priority.
-
Safety comes before the house and before the insurance claim.
If the fire has just occurred, make sure everyone—including family members and pets—is accounted for and safely away from the structure. Call 911 if emergency services have not already been notified.
Never re-enter a fire-damaged building simply to retrieve belongings, paperwork, medications, photographs, or other possessions unless the appropriate authorities have determined that it is safe to enter.
A structure can remain dangerous even after the visible flames have been extinguished. Fire can weaken structural components, damage electrical systems, create unstable ceilings or flooring, and leave behind smoke, soot, contaminated water, broken glass, sharp debris, and other hazards.
If anyone has suffered burns, breathing difficulties, significant smoke exposure, or another injury, seek appropriate medical attention.
Do not assume that "the fire is out" means "the house is safe."
Firefighters or other authorities may restrict access to portions—or all—of the property. Follow those instructions.
There will be time to document your belongings.
There will be time to address your insurance claim.
There is nothing inside the property worth risking another injury.
-
Once authorities determine that you can safely access the property, one of your most important priorities should be documentation.
Fire scenes can change rapidly.
Emergency board-up companies may arrive. Water mitigation may begin. Damaged drywall or insulation may need to be removed. Contents may be moved. Debris may be discarded. Contractors may begin temporary repairs.
Some of those actions may be necessary to protect the property—but they can also change the physical evidence showing what the property looked like immediately after the fire.
Photograph and video the property extensively.
Whenever safely possible, document:
Every affected room
Walls and ceilings
Flooring
Windows and doors
Cabinetry
Appliances
Furniture
Personal belongings
Visible smoke and soot
Burned and charred materials
Firefighter water damage
Wet building materials
Damaged electrical components
Exterior damage
Roof damage
Areas accessed or opened by firefighters
Debris
Damaged contents
Areas that appear affected even though flames never reached them
Do not focus exclusively on the room where the fire started.
Smoke, soot, heat, odor, and water can travel far beyond the fire's area of origin. Photograph adjoining rooms and other portions of the home as well.
Video can be particularly valuable because it allows you to slowly walk through the property while describing what you are seeing. You can identify rooms, belongings, visible damage, odors, standing water, and other conditions that may become harder to remember weeks or months later.
Do not be too quick to throw things away.
A burned sofa may look like garbage to you, but during an insurance claim it is also evidence of property that existed before the loss.
The same can be true of clothing, electronics, furniture, appliances, tools, kitchenware, children's belongings, decorations, and hundreds of other household items.
There will certainly be circumstances where damaged material must be removed for health, safety, emergency mitigation, or other legitimate reasons. When that occurs, document it as thoroughly as reasonably possible before disposal.
Photographs are inexpensive.
Lost evidence can be impossible to recreate.
-
Your insurance carrier should generally be notified of the loss promptly.
When reporting the fire, provide accurate basic information about what occurred. You do not need to diagnose every form of damage or know the complete cost of the loss during the initial telephone call.
At this stage, you may not even know the full extent of the damage.
Obtain and save your:
Claim number
Insurance company's contact information
Assigned adjuster's name and contact information
Date and time the claim was reported
Confirmation or reference numbers
Instructions provided by the carrier
From this point forward, begin maintaining a simple claim communication log.
Whenever you communicate with someone about the claim, record:
Date — Time — Person — Company — What Was Discussed — What Happens Next
Insurance claims can continue for weeks or months. What seems impossible to forget today can become surprisingly difficult to remember several months from now.
Be accurate, but don't speculate.
You may know that there was a fire in the kitchen, for example, but you may not know precisely what caused it.
If you don't know something, it is perfectly reasonable to say that you don't know.
Fire origin and cause can involve technical questions and, depending upon the circumstances, may be investigated by fire officials, insurance representatives, engineers, electricians, investigators, or other professionals.
Your job during the initial reporting process is to provide truthful information based upon what you actually know—not to solve the investigation yourself.
-
Homeowners insurance policies commonly contain duties requiring policyholders to take reasonable steps after a loss to protect the property from additional damage.
For a fire-damaged home, this may involve emergency services such as:
Boarding broken windows and doors
Securing openings
Installing temporary roof protection
Extracting standing water
Beginning structural drying
Removing water-saturated materials when appropriate
Securing the property against unauthorized entry
Addressing immediate electrical or structural hazards
Protecting salvageable belongings from additional damage
The key concepts are reasonable, necessary, documented, and safe.
You are not expected to climb onto a dangerous roof, enter an unstable building, or personally perform specialized restoration work.
Qualified professionals may be necessary.
Firefighter water damage deserves special attention.
The fire may have started in one room, but the water used to extinguish it can migrate into completely different areas.
Water can travel:
Through ceilings
Inside wall cavities
Under flooring
Into cabinetry
Through insulation
Between floors
Into adjoining rooms
Materials that appear normal from the surface can sometimes contain significant moisture.
Prompt water mitigation can therefore be an important part of preventing secondary damage.
But mitigation and reconstruction are not the same thing.
Emergency work necessary to protect the property should not automatically be confused with committing to a complete reconstruction project.
Before signing substantial contracts, understand:
What work is being authorized
What the company will charge
How pricing is determined
Whether you are personally responsible for charges not paid by insurance
Whether you are assigning any insurance benefits or rights
Whether the agreement includes reconstruction
How the contract can be cancelled
What happens to damaged materials and contents
A disaster creates urgency.
Urgency should not eliminate informed decision-making.
-
If the home cannot safely be occupied after the fire, you may suddenly incur expenses that did not exist before the loss.
Depending upon your insurance policy and circumstances, your policy may include Additional Living Expense (ALE) or similar coverage intended to address certain increased costs associated with maintaining your household while the insured residence is uninhabitable because of a covered loss.
Start keeping records immediately.
Potential expenses might include:
Hotel accommodations
Temporary housing
Increased meal expenses
Laundry
Additional transportation
Pet boarding
Moving expenses
Storage
Emergency clothing
Necessary household items
Temporary repairs
Other increased living expenses resulting from displacement
Coverage varies considerably by policy and circumstance, and not every expense incurred after a fire is necessarily reimbursable.
Nevertheless, save the receipt.
Create a physical folder, digital folder, spreadsheet, or combination of all three.
For every expense, record:
Date | Vendor | Amount | Purpose | Receipt
If you normally spend money on something regardless of the fire, the insurance treatment may be different from a new or increased expense caused by displacement. Good records make those distinctions much easier to establish later.
VIP Expert Insight
Don't wait until the end of the month to reconstruct what you spent.
Record expenses as they occur.
A five-minute routine each evening can prevent hours of searching through bank statements and emails months later.
-
For many families, documenting personal property becomes one of the most time-consuming parts of a major fire insurance claim.
Think about everything inside a typical home.
Clothing.
Shoes.
Furniture.
Televisions.
Computers.
Kitchenware.
Small appliances.
Tools.
Books.
Toys.
Linens.
Decorations.
Sporting equipment.
Collectibles.
Garage contents.
Outdoor equipment.
Personal items accumulated over decades.
A significant fire can affect hundreds or even thousands of individual items.
Don't try to remember everything from memory in one sitting.
Work room by room.
Start with one area and systematically document what was present.
For each item, gather as much information as reasonably available, such as:
Item description
Quantity
Manufacturer
Brand
Model
Approximate age
Purchase location
Original cost, if known
Replacement cost information
Condition before the fire
Photographs
Receipts or other proof of purchase, when available
You may not have receipts for everything you own.
That's normal.
Other documentation may sometimes help establish ownership or identify property, including photographs taken before the fire, online purchase histories, email receipts, credit-card records, warranty registrations, manuals, product packaging, family photographs, and videos of the home.
Don't forget ordinary belongings.
People naturally remember expensive items such as televisions and furniture.
They often forget the hundreds of smaller things.
Open a kitchen cabinet mentally and imagine everything inside it:
Plates, bowls, glasses, coffee mugs, cookware, utensils, baking supplies, food-storage containers, spices, small appliances and dozens of other items.
Now multiply that by every closet, drawer, bathroom, bedroom, garage, office and storage area in the house.
Those smaller items can represent substantial value collectively.
-
After a fire, homeowners can suddenly find themselves surrounded by decisions.
Restoration companies.
Contractors.
Insurance representatives.
Contents companies.
Temporary housing providers.
Board-up companies.
Cleaning companies.
Friends.
Family.
Neighbors.
Everyone may have advice.
Some decisions truly are urgent.
Many are not.
Before signing contracts or authorizing substantial work, make sure you understand exactly what you are agreeing to.
Be particularly careful about irreversible decisions.
Once damaged materials have been demolished, contents discarded, surfaces cleaned, or reconstruction completed, the original condition of the property may no longer be available for inspection.
That's another reason documentation is so important.
Similarly, don't automatically assume that something must be cleaned simply because someone says it can be cleaned—or that something must be replaced simply because it looks damaged.
Fire restoration can involve technical questions regarding the material involved, the type of residue, extent of contamination, restoration methods, manufacturer recommendations, cost, safety, and whether restoration can reasonably return the item to its pre-loss condition.
Don't assume that something is covered—or excluded—without reviewing the policy.
Insurance policies are contracts.
The answer to a coverage question can depend upon the actual policy language, endorsements, exclusions, limits, deductibles, cause of loss, and specific circumstances surrounding the claim.
What happened in your neighbor's claim does not necessarily determine what happens in yours.
And something an insurance representative, contractor, friend, or internet article says generally about insurance should never substitute for reading the policy that actually insures your property.
-
You do not need to become an insurance expert overnight.
You should, however, understand the decisions you are being asked to make.
A significant fire claim can involve numerous professionals, including:
Insurance adjusters
Public adjusters
Fire investigators
Engineers
Restoration contractors
General contractors
Water mitigation companies
Contents specialists
Industrial hygienists or environmental professionals
Electricians
Plumbers
Roofing contractors
Temporary housing providers
Mortgage companies
Attorneys, when necessary
Each professional has a different role.
Understanding who they represent and what they are responsible for can prevent considerable confusion.
The insurance company's adjusters and consultants are working on behalf of the insurance carrier.
A public adjuster, by contrast, is retained by the policyholder to assist with documenting, preparing, presenting, and negotiating the property insurance claim, subject to the laws and licensing requirements of the applicable state.
Whether or not you ultimately hire a professional, you should feel comfortable asking questions.
What does my policy cover?
What is my deductible?
Do I have replacement cost coverage?
What happens to depreciation?
Do I have Additional Living Expense coverage?
Who is documenting the building damage?
Who is documenting my contents?
How will smoke contamination be evaluated?
How will hidden water damage be addressed?
What happens next?
If someone cannot explain an important decision in a way that you understand, ask them to explain it again.
This is your home and your insurance claim.
You should understand the process.
-
Smoke Travels Much Farther Than Flames
A room does not necessarily have to burn to be affected by a fire.
Smoke can migrate throughout a home through open spaces, penetrations, attic areas, and mechanical systems. Residue may settle on walls, ceilings, furniture, fixtures, electronics, clothing, and other contents far from the fire's origin.
That is why evaluating a fire loss should not automatically stop at the visibly burned portion of the property.
-
The water used to save your home can create another substantial category of damage.
Drywall may become saturated. Insulation can retain moisture. Wood flooring can swell or cup. Cabinetry may absorb water. Moisture can migrate beneath finishes or into wall and floor assemblies where it is not readily visible.
This does not mean every wet material automatically requires replacement.
It means the full extent of water migration should be identified and appropriately evaluated rather than assuming that areas without visible fire damage are unaffected.
-
After a major fire, individual expenses can seem insignificant compared with the damage to the home.
Six months later, those expenses can represent thousands of dollars.
Keep receipts for temporary housing, meals, laundry, transportation, emergency purchases, pet accommodations, moving, storage, temporary repairs, and other fire-related expenses.
If you're unsure whether something will qualify under your policy, keep the documentation anyway and determine coverage later.
You can always decide that a receipt isn't needed. You cannot recreate a receipt you threw away months ago.
-
During the first 24 hours, try to avoid making decisions that unnecessarily complicate your recovery or insurance claim.
Don't discard damaged belongings before documenting them.
Photograph and inventory damaged property before disposal whenever reasonably possible and safe to do so.
Don't clean smoke and soot simply to "see if it comes off."
Different combustion residues can require different cleaning methods, and inappropriate cleaning can sometimes make staining or damage worse. Document conditions before cleaning begins.
Don't photograph only the burned room.
Document the entire affected property, including areas impacted by smoke, soot, odor, water, heat, and emergency response activities.
Don't sign major contracts simply because you feel pressured to act immediately.
Emergency stabilization may genuinely be urgent. Long-term reconstruction decisions usually deserve careful consideration.
Don't forget your living expenses.
Begin tracking displacement-related costs from day one.
Don't assume that only visibly burned materials matter.
A comprehensive fire loss evaluation considers fire, heat, smoke, soot, water, odor, structural effects, contents, and potentially hidden damage.
-
You do not need to rebuild your home today.
You do not need to know the final value of your insurance claim today.
You do not need to inventory every possession today.
And you do not need to understand every provision of a lengthy insurance policy today.
Your first 24 hours should be about establishing control over a situation that suddenly feels out of control.
Protect your family.
Document the property.
Report the loss.
Prevent additional damage when reasonably possible.
Keep your receipts.
Begin preserving information about your belongings.
Avoid rushed, irreversible decisions.
Ask questions and understand your options.
The fire may have occurred in minutes, but recovery is a process. Taking that process one step at a time—and creating good records from the very beginning—can make the weeks and months ahead considerably easier.
You Focus on Your Family. We'll Help You Understand the Claim.
At VIP Adjusting, our philosophy is simple: education comes before representation.
Before asking a policyholder to make a decision about working with us, we want them to understand their policy, the condition of their property, the insurance claim process, the potential challenges ahead, and the options available to them.
That's why we offer complimentary property inspections, policy reviews, claim evaluations, and consultations. If you've recently experienced a fire, you're welcome to speak with us whether you're ready to hire a public adjuster, simply have questions, or aren't yet sure what kind of help you need.
The first step isn't signing a contract. It's understanding what comes next.
Fire damage isn't always limited to what was directly burned. Learn how smoke, soot, firefighting water, odor and other forms of damage can affect a property and its contents after a fire, including damage that may not be immediately visible. VIP Adjusting explains why understanding the full extent of a fire loss is an important part of the property insurance claim and recovery process.
Understanding Fire & Smoke Damage
-
A house fire is one of the most devastating events a homeowner can experience. While the visible flames may only affect one portion of the structure, the damage rarely stops where the fire started. Heat, smoke, soot, water used to extinguish the fire, and corrosive combustion byproducts can spread throughout the property, affecting areas that may appear untouched at first glance.
Every fire is unique. The cause of the fire, the materials that burned, how long the fire burned, and the methods used to extinguish it all influence the extent of the damage. Even relatively small fires can create widespread smoke contamination, lingering odors, hidden moisture, and damage to personal belongings throughout the home.
For many homeowners, the greatest surprise is discovering that the most significant damage is not always caused by the flames themselves. Smoke and soot can travel through hallways, open doorways, attic spaces, HVAC systems, and other concealed pathways, leaving microscopic particles on walls, ceilings, furniture, electronics, clothing, and personal possessions. At the same time, thousands of gallons of water may be used to extinguish the fire, creating an entirely separate category of damage that often requires immediate drying and mitigation.
Recovering from a fire involves much more than rebuilding burned areas. It requires identifying every category of damage, documenting the full extent of the loss, understanding what your insurance policy may provide coverage for, and developing a comprehensive restoration plan that returns your property to its pre-loss condition whenever possible.
Although every insurance policy is different, many fire losses involve several different types of damage that must be evaluated individually. Understanding these categories is an important first step toward navigating the claims process and ensuring nothing is overlooked.
Fire Damage
Fire damage refers to the direct destruction caused by flames and intense heat. Structural framing, roofing materials, drywall, cabinetry, flooring, windows, and countless other building components may be partially or completely destroyed. In many cases, even materials that appear intact may have been weakened by heat exposure and require further evaluation.
Smoke Damage
Smoke can spread rapidly throughout a structure, often reaching rooms that were never touched by flames. As smoke cools, it deposits fine particles on nearly every surface it encounters. Depending on what burned, smoke residue can discolor walls and ceilings, contaminate HVAC systems, penetrate porous materials, and leave persistent odors that require specialized cleaning techniques.
Soot Damage
Soot consists of microscopic carbon particles produced during incomplete combustion. These residues are often acidic and may continue damaging surfaces if they are not properly removed. Soot can stain finishes, corrode metals, damage electronics, discolor fabrics, and permanently affect delicate materials if left untreated.
Water Damage
Ironically, firefighters often use hundreds—or even thousands—of gallons of water to save a structure from complete destruction. While these efforts are essential, the water itself can saturate drywall, insulation, flooring, cabinetry, and personal belongings. Without prompt drying and mitigation, secondary issues such as microbial growth, swelling, warping, and deterioration may develop.
Odor Damage
Smoke odors frequently linger long after visible damage has been cleaned. Odor molecules can become embedded in insulation, wood framing, carpeting, upholstery, HVAC ductwork, and personal belongings. Proper odor removal often requires specialized equipment and restoration techniques beyond ordinary cleaning.
Hidden Damage
Not all fire damage is immediately visible. Elevated temperatures can weaken structural components, smoke can infiltrate concealed cavities, moisture can become trapped behind walls, and electrical systems may suffer damage that requires further inspection. A thorough evaluation is often necessary to identify conditions that cannot be seen during a simple visual inspection.
Fire Damage Is More Than What You Can See
One of the most common misconceptions after a fire is that the damage is limited to the areas where flames were visible. In reality, a fire loss is often a combination of multiple interrelated forms of damage occurring simultaneously. Properly identifying and documenting each category is an important part of understanding the full scope of the loss and helping ensure that no aspect of the damage is inadvertently overlooked during the claims process.
VIP Expert Insight
The room where the fire started is often only the beginning of the story. Heat, smoke, soot, water, and odor frequently travel well beyond the area of origin, affecting portions of the home that may initially appear undamaged. A comprehensive inspection should evaluate the property as a whole—not just the areas with visible burn damage.
Steps to Success
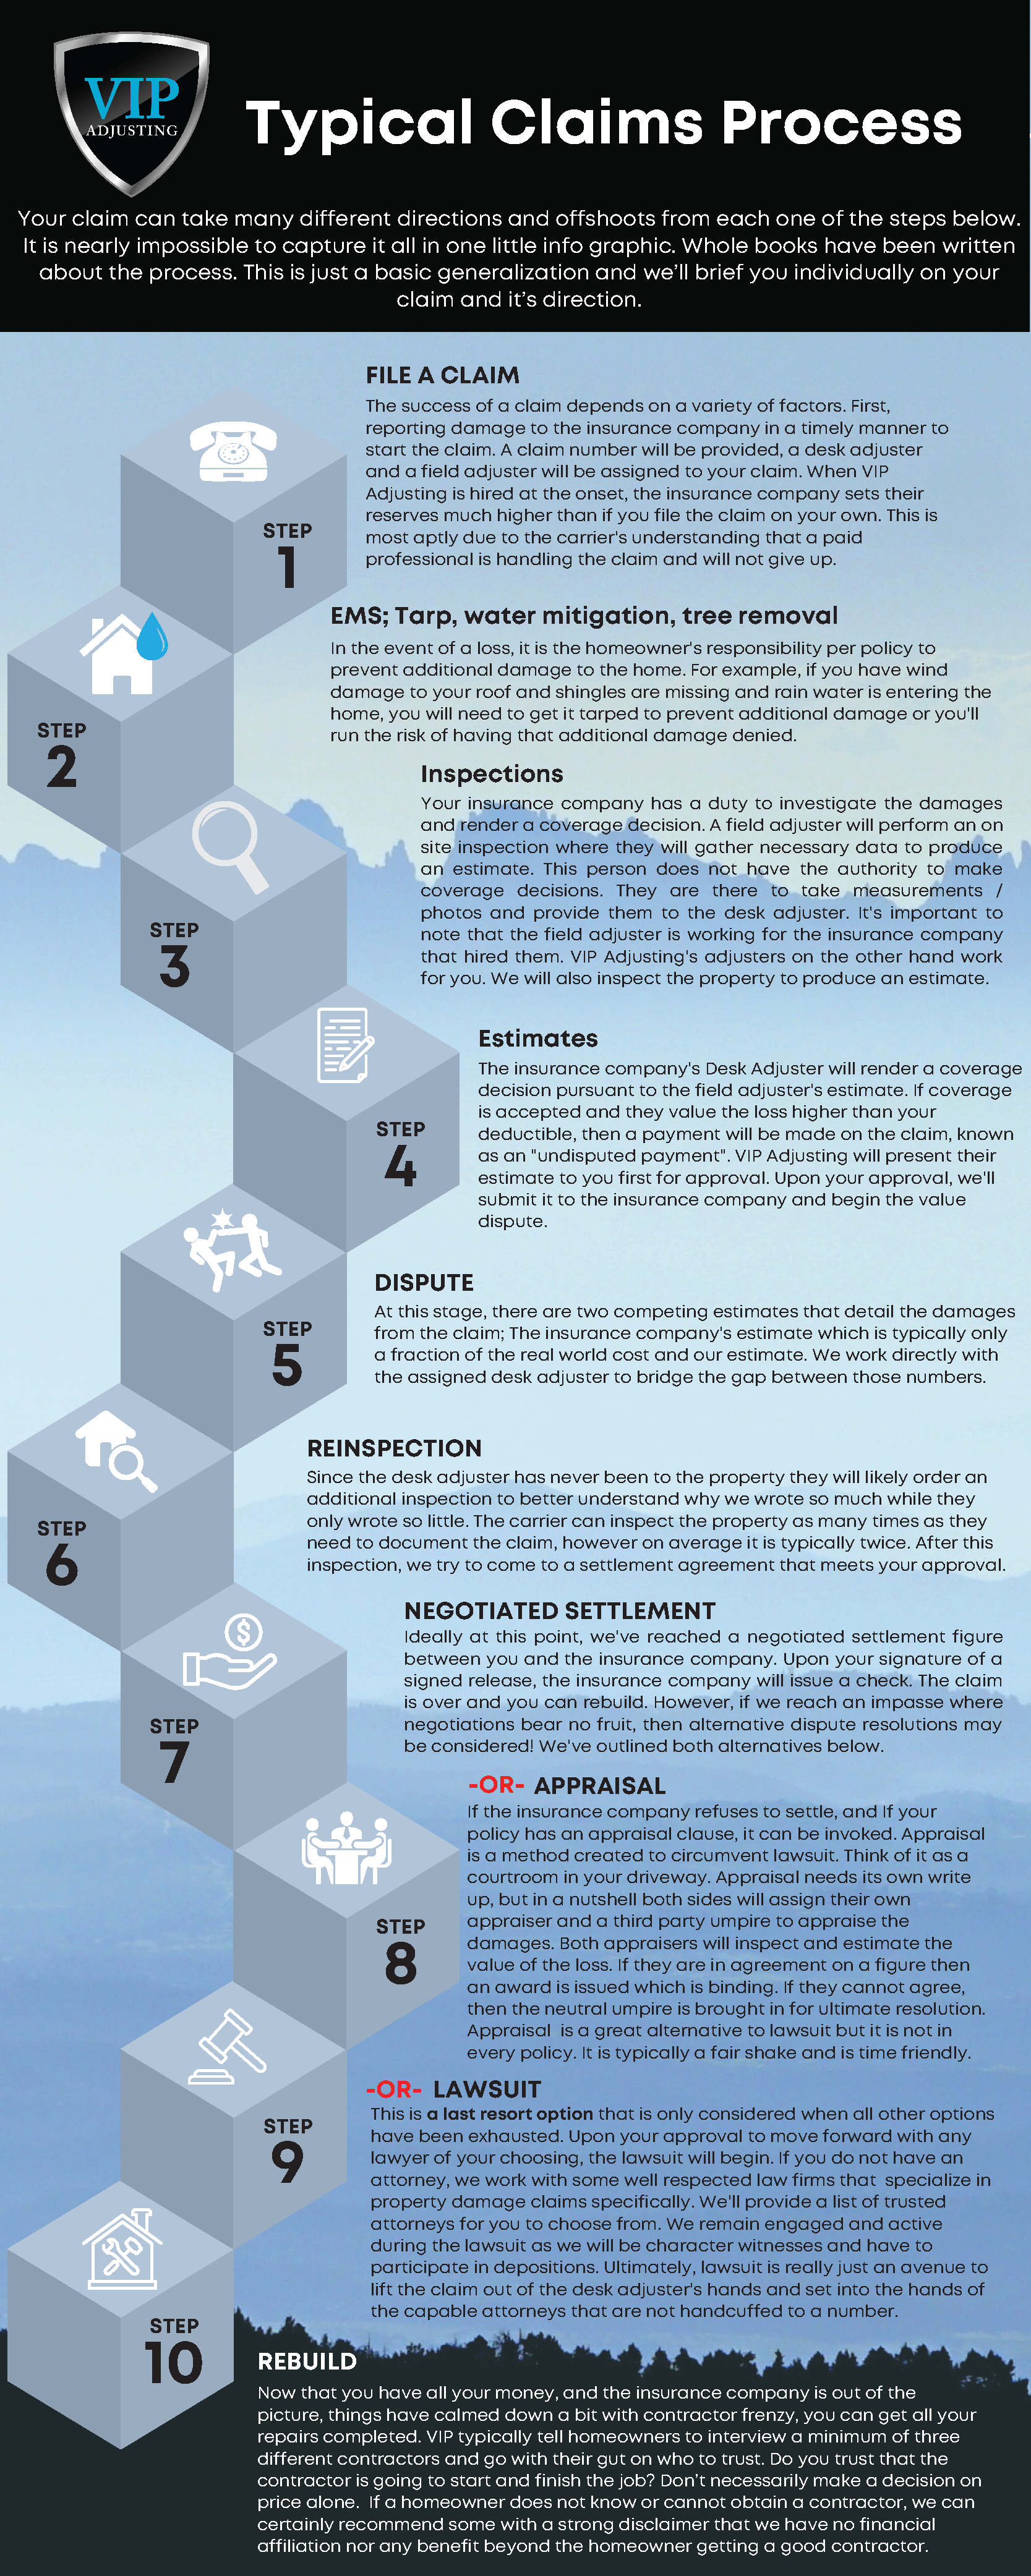
Video teaching about the Insurance Claims ProceA fire damage insurance claim can involve numerous steps, inspections and professionals before a property is ultimately repaired or rebuilt. After the initial claim is reported, emergency services may be needed to secure the property and prevent additional damage. Restoration professionals, hygienists, engineers, textile specialists and other experts may also become involved depending on the circumstances of the loss.
As the claim progresses, the insurance company will typically inspect the property and prepare its evaluation of the damage. The policyholder may also obtain independent estimates and documentation. Differences in the scope or value of the loss can lead to additional inspections, negotiations and, in some cases, dispute-resolution processes such as appraisal or litigation.
Watch the video for a step-by-step overview of the typical fire damage insurance claim process—from filing the claim and emergency mitigation through inspections, estimates, negotiations, settlement and rebuilding.ss
Insurance Claims Process
Click each step within the infographic on the right to read more about each individual step. This is a basic example of a claims process. There are mini-steps in between the steps listed, but for purposes of understanding the claim process, this is the minimum one needs to know.
Steps:
File a Claim
Ems; Tarp, Testing & Restoration
Inspections
Estimates
Dispute
Reinspection
Negotiated Settlement
Appraisal or…
Lawsuit
Rebuild
Articles, Resources and Downloads
Smoke Damage
Insurance Coverage
Smoke damage can extend far beyond the area directly affected by flames. Smoke can travel through openings, electrical outlets, wall cavities, attics, ceiling spaces and other areas where air can move, sometimes creating damage that is not immediately visible.
Evaluating smoke damage may require more than simply looking for discoloration or noticing an odor. Depending on the circumstances, independent testing can help identify contamination and provide documentation that can be used to develop an appropriate remediation protocol. Professional restoration may involve specialized cleaning methods, air scrubbers, HEPA filtration, hydroxyl generators and other equipment designed to address smoke and odor.
Watch the video to learn how smoke can travel through a property, where hidden smoke damage may be found, and how testing and professional remediation can help determine the appropriate cleanup process.
Understanding Fire Damage
Watch this video for an some important information related to fire damage.
The fire is as devastating as one can imagine. The last thing anyone wants to think about after a fire is how insurance works, what’s covered in the policy, and will you and your family be taken care of.
Smoke damage can extend far beyond the area directly affected by flames. Smoke can travel through openings, electrical outlets, wall cavities, attics, ceiling spaces and other areas where air can move, sometimes creating damage that is not immediately visible.
Evaluating smoke damage may require more than simply looking for discoloration or noticing an odor. Depending on the circumstances, independent testing can help identify contamination and provide documentation that can be used to develop an appropriate remediation protocol. Professional restoration may involve specialized cleaning methods, air scrubbers, HEPA filtration, hydroxyl generators and other equipment designed to address smoke and odor.
Watch the video to learn how smoke can travel through a property, where hidden smoke damage may be found, and how testing and professional remediation can help determine the appropriate cleanup process.
Smoke Damage
Smoke damage is sometimes incredibly apparent, visual and detectible by our senses. However, smoke reaches everywhere that air goes. It settles on virtually everything as it spreads throughout the building via the HVAC system and or general air movement.
This video will cover some issues that arise from smoke damage, the health effects, the importance of independent third party testing along with proper smoke mitigation, etc.
Soot damage is often overlooked because it may not immediately look severe. Fine particles can settle across furniture, flooring, walls, contents and mechanical systems, sometimes making an entire surface appear darker without the property owner realizing how much residue is present.
Soot can affect many areas of a property, including wood and stone flooring, personal property, furnishings and HVAC components. Because the contamination may extend well beyond the area directly affected by flames, evaluating and cleaning soot often requires professional attention.
Watch the video to learn how soot can spread throughout a property, why it may be difficult to see, and why it should be considered when evaluating the full extent of a fire loss.
Soot - an overlooked carcinogen
Watch this video for an some important information related to fire damage.
The fire is as devastating as one can imagine. The last thing anyone wants to think about after a fire is how insurance works, what’s covered in the policy, and will you and your family be taken care of.
Water damage is often an overlooked part of a fire loss. Firefighters may need to use a significant amount of water to extinguish the fire, and that water can travel well beyond the area directly affected by flames. Floors, walls, contents and adjoining rooms may all be affected.
Fire-related water damage can also come from other sources. Intense heat may damage or rupture plumbing lines, allowing water to continue flowing after occupants have evacuated. Appliances and other items that contain water may also release water when damaged by fire or heat.
Watch the video to learn how firefighting water, burst pipes and other sources of water damage can become part of a fire loss—and why the specific facts and insurance policy should always be reviewed.
Water Damage
Smoke damage is sometimes incredibly apparent, visual and detectible by our senses. However, smoke reaches everywhere that air goes. It settles on virtually everything as it spreads throughout the building via the HVAC system and or general air movement.
This video will cover some issues that arise from smoke damage, the health effects, the importance of independent third party testing along with proper smoke mitigation, etc.
What Does Insurance cover?
What Does it not cover?
Where does it leave me?
It’s incredibly frustrating to read a policy after a loss and try to decipher the legal jargon on what is and what is not covered. Most people throw the hands up and yell “I don’t get it, I buy insurance and pay them every month, ALL damage should be covered beyond my deductible no matter the cause”. This would be wonderful if it were the case. However, it’s the complete opposite. The policy might state that water loss is covered, but it’s capped at 10k; Your flooring is damaged but they will only cover the portion that is damaged because you have a cosmetic endorsement even though your flooring goes throughout the dwelling and they don’t make it anymore which renders it impossible to match; or you realize that none of your contents are covered because you never included contents in your policy. Whatever the scenario, it’s important to find out what is covered in your policy and set your expectations.
Submit your policy here and VIP Adjusting will perform a Policy Analysis and send you a full report on coverage in layman’s terms
Recovering from a serious fire loss rarely happens overnight. Depending on the circumstances, a claim may involve insurance adjusters, restoration companies, hygienists, engineers, contractors, public adjusters and other professionals, each handling a different part of the recovery process.
Multiple inspections, documentation, policy review, restoration work, estimates and negotiations can all take time. If disagreements arise regarding coverage, the scope of damage or the value of the loss, the process may take even longer. There is no single timeline that applies to every fire insurance claim.
The key is to stay informed, choose qualified professionals, maintain good communication and understand what is happening at each stage of the process. Watch the video for a realistic overview of what property owners may experience as they move from the initial fire toward resolution and rebuilding.
Trusting the Process
Sticking through a property damage insurance claim takes Grit, Determination, Trust and an Iron Stomach to successfully arrive to the end where indemnification is. Patience and Trusting the Process are two of the biggest virtues that will be your guiding light. We at VIP Adjusting are fully committed to transparency, excellent communication, steady and regular updates regarding the claim. The most important part in any service and consulting industry is communication. Our Clients are never in the dark. Instead we illuminate every nook and cranny with constant work and communication on the claim.
Case Studies
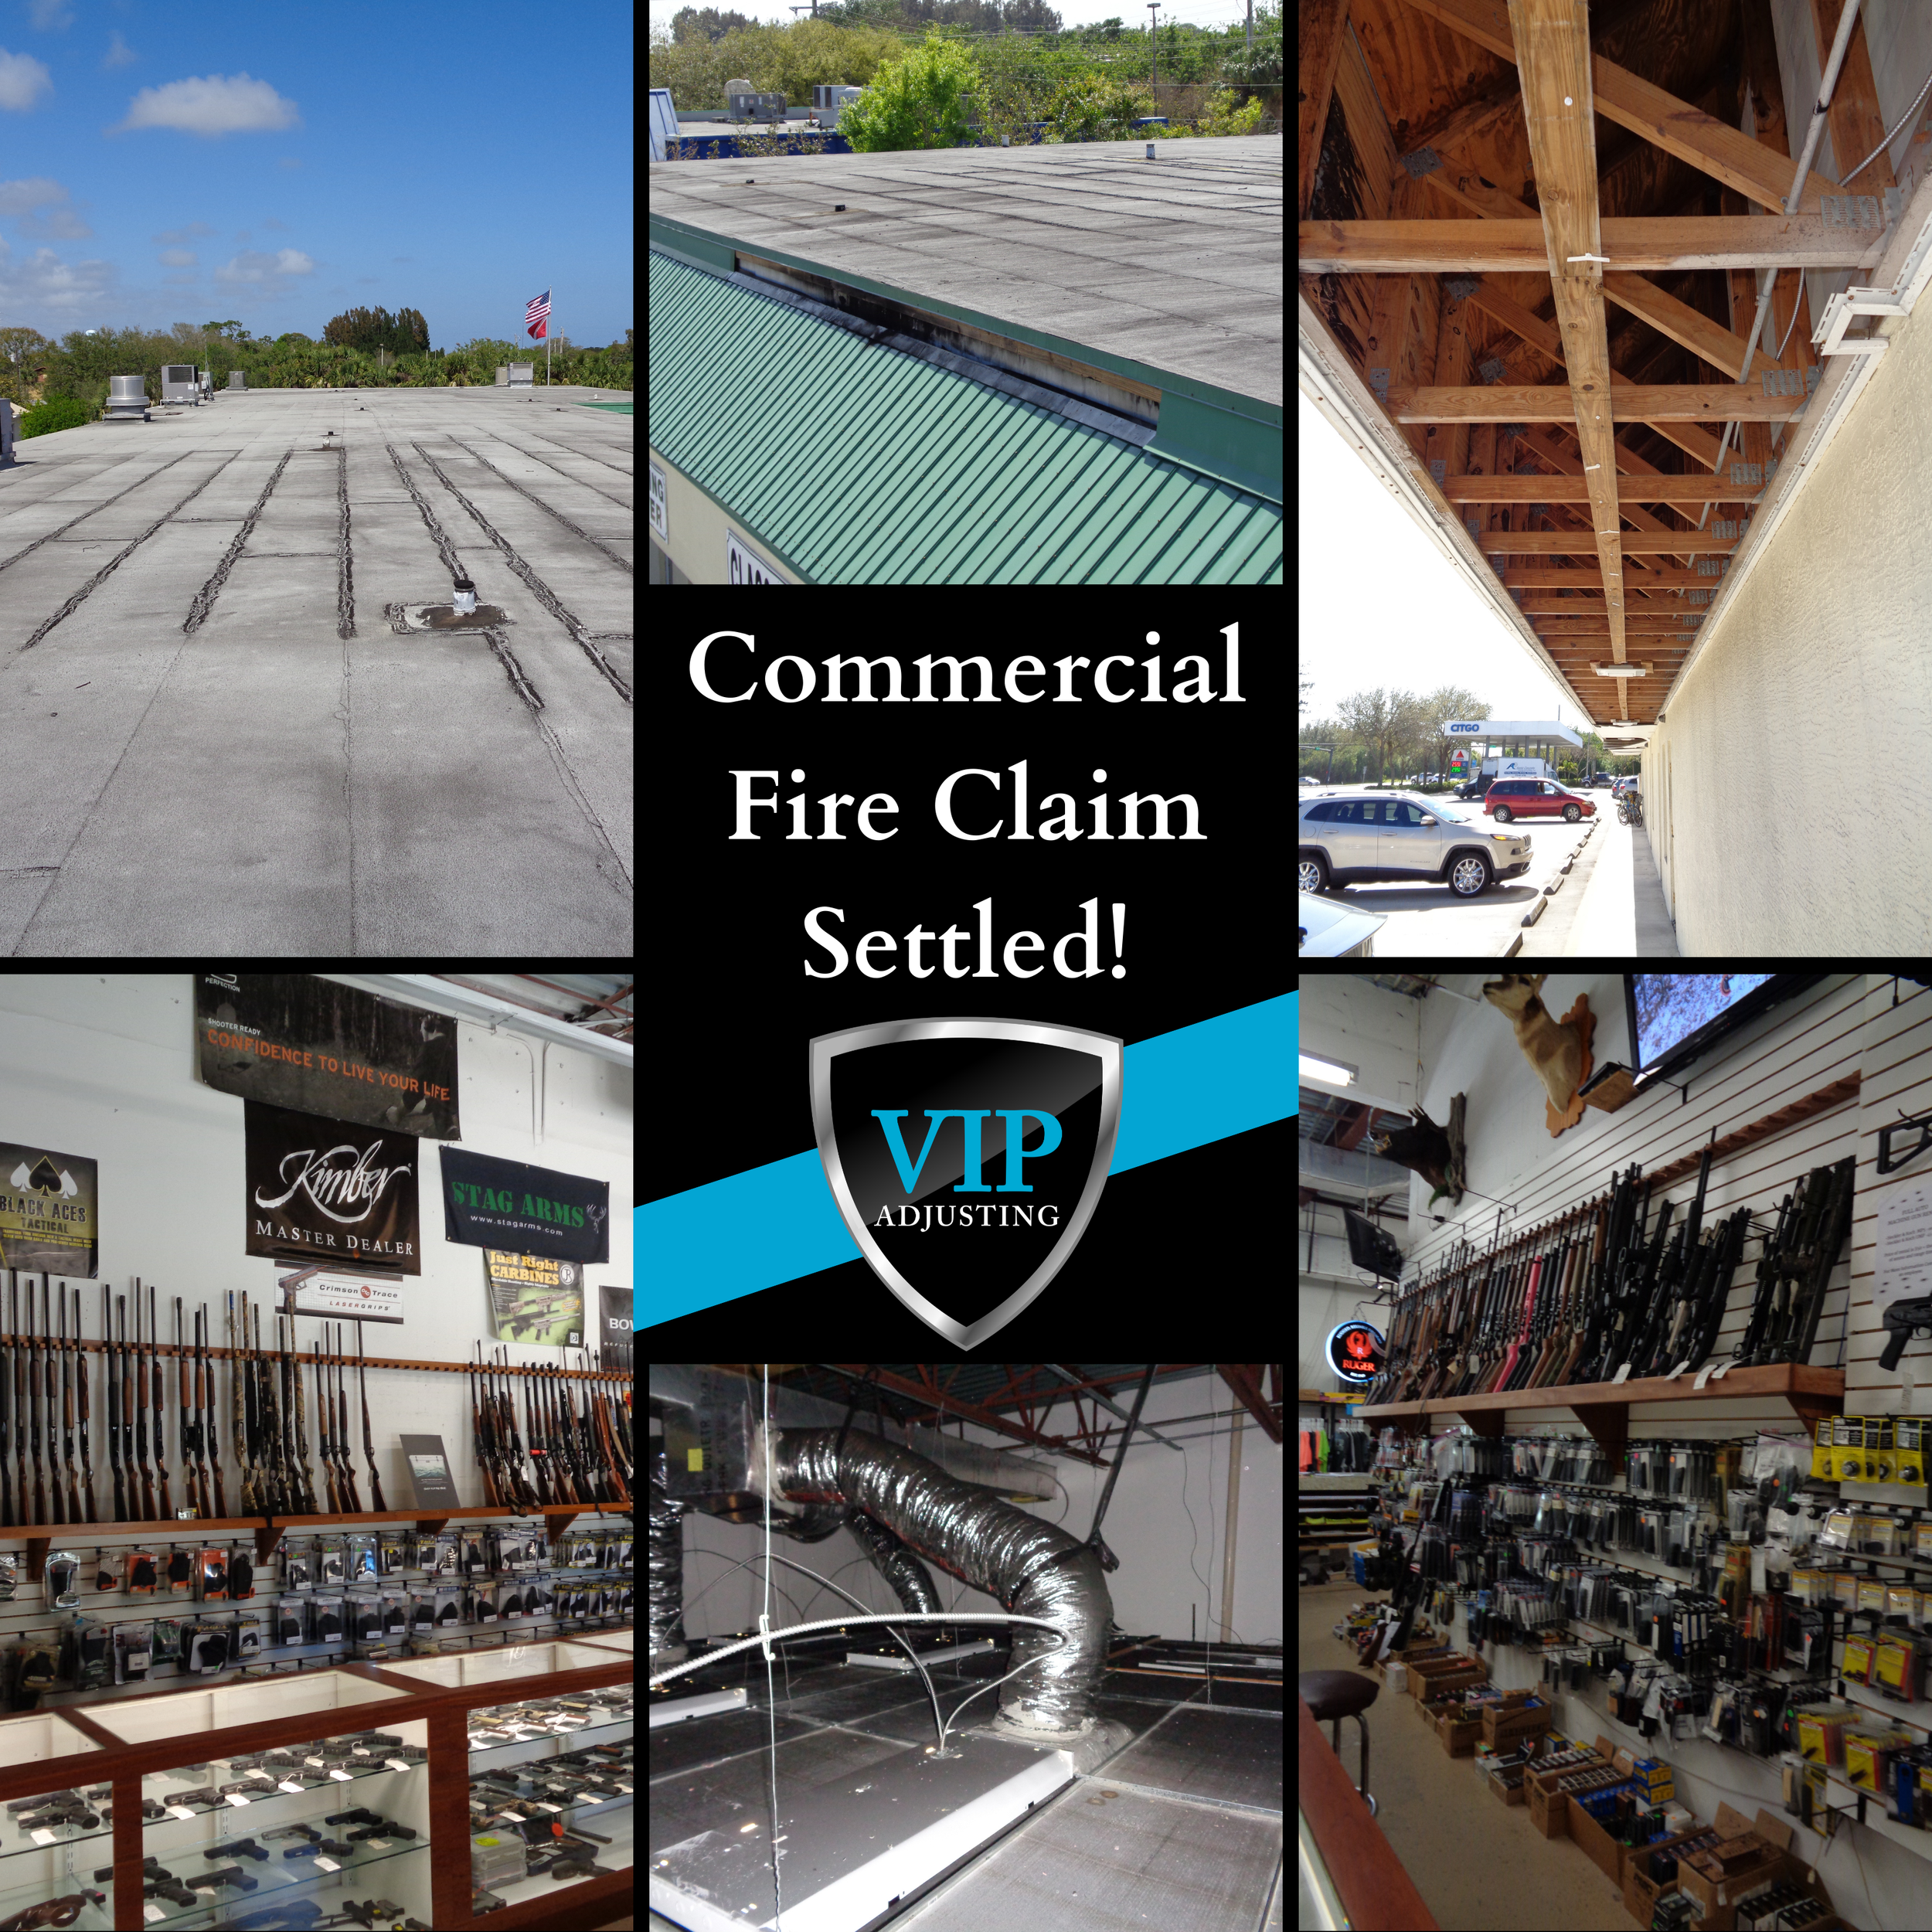
Read Here about how VIP Adjusting settled a claim for over a million dollars for the business owner.
Before we were involved, the insurance company offered the insured only 20k.
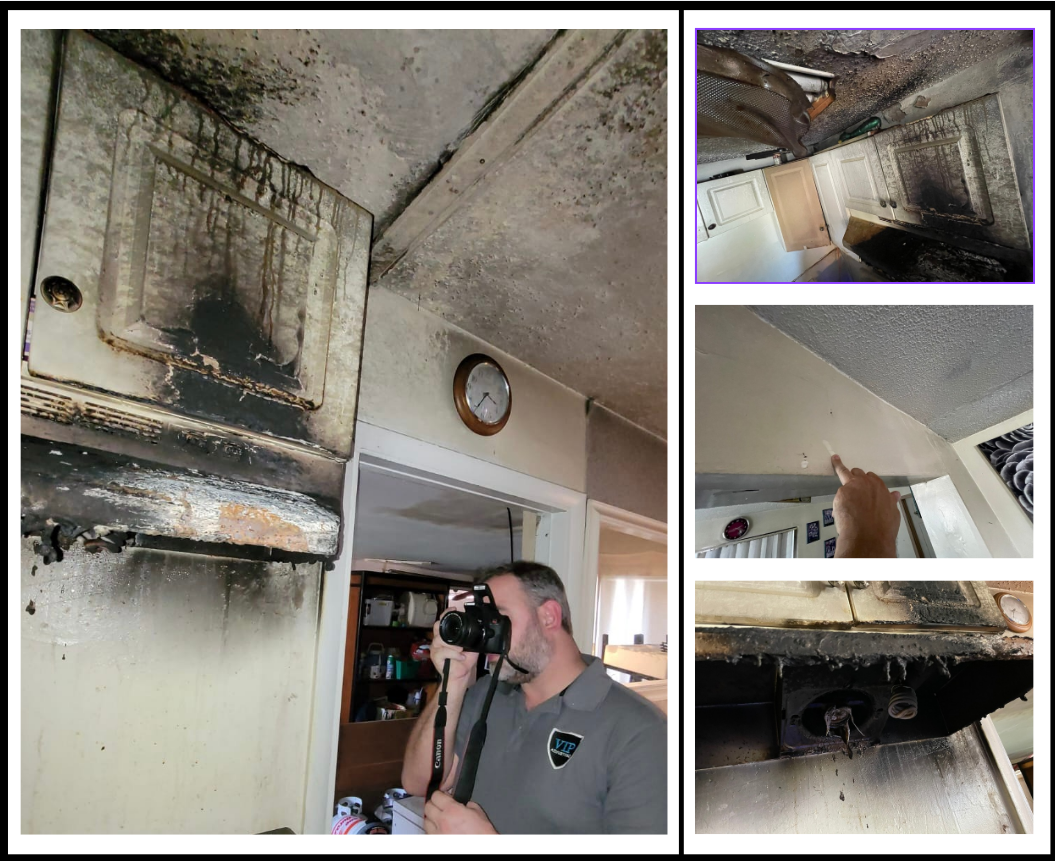
From $5,000 to $55,000. Read how VIP Adjusting obtained 10x what the insurance company’s 1st offer.
A small kitchen fire can cause a lot of damage.
From $5,000 to $55,000. Read how VIP Adjusting obtained 10x what the insurance company’s 1st offer.
A small kitchen fire can cause a lot of damage.
A Brief History of Property Insurance
Property insurance has existed in one form or another for centuries, but many of the principles that shape today's homeowners insurance can be traced to devastating urban fires that changed the course of history. Following events such as the Great Fire of London in 1666—which destroyed more than 13,000 homes and businesses—communities began recognizing the need for organized systems to help people recover financially after catastrophic losses. These disasters laid the foundation for the modern concept of property insurance.
In the United States, one of the most influential figures in the development of fire insurance was Benjamin Franklin. In 1752, Franklin helped establish the Philadelphia Contributionship for the Insurance of Houses from Loss by Fire, America's first successful mutual fire insurance company. Beyond simply providing financial protection, the organization promoted safer construction practices and encouraged fire prevention—principles that continue to influence the insurance industry today.
As property insurance evolved over the following centuries, policies became more sophisticated, covering not only fire damage but also windstorms, water damage, hurricanes, theft, and many other causes of loss. At the same time, the claims process became increasingly complex, creating a need for professionals who could help policyholders understand their coverage, document their losses, and navigate the often-challenging insurance claims process. This evolution ultimately gave rise to the public adjusting profession, which exists to represent the interests of policyholders throughout the adjustment of a property insurance claim.
Today, property insurance protects millions of homeowners and businesses across the country. While policies have become more comprehensive than ever before, understanding coverage and navigating the claims process can still be overwhelming after a disaster. That's why we believe education is the first step toward recovery. The better informed a policyholder is, the better equipped they are to make confident decisions and protect their interests after a loss.
Want to learn more? Read our complete article on the history of property insurance and how the public adjusting profession evolved to advocate for policyholders.
Need Assistance?
If you've experienced property damage and need assistance with your insurance claim, fill out the form below. Whether it's a new claim or you're having trouble with an existing one, our team is here to help guide you through the process and ensure you get the compensation you deserve.
