Hurricane Isaias Damage in Pensacola?Get a Licensed Florida Public Adjuster on Your Side.
We help homeowners and businesses document the damage, prepare the claim and negotiate with the carrier.
Our Florida Panhandle team is available now.
We handle flood claims too. Storm surge and rising water, for owners with flood coverage.
Request received.
A member of our Panhandle team will contact you. Need help right now? Call (850) 600-4154.
- Licensed Florida Public Adjusters
- Florida Panhandle Team
- 24/7 Storm Response
- Licensed Florida Building Contractor
- 5-Star Client Reviews
Wind. Water. Flood.
Isaias can cause all three. We handle claims for every one of them.
WIND
Hurricane winds can damage roofing, siding, soffit, fascia, windows, doors and exterior components, including damage that isn't obvious from the ground.
WATER
Wind-driven rain and storm-created openings can affect insulation, ceilings, drywall, flooring, cabinets and contents.
SURGE & FLOOD
Storm surge and rising water may involve separate flood coverage. We handle flood claims, including losses where wind and water both did damage.
Seeing any of this at your property?
Call (850) 600-4154Commercial Property, Condo or HOA Damage?
We handle hurricane claims for commercial buildings, condominium associations and HOAs: roofs, common elements, building envelopes and business interruption, plus unit owners where the master policy stops and theirs begins.
Talk to Our Panhandle TeamOne Storm. Two Policies. Both Handled.
After a hurricane, the same home often has wind damage and flood damage. They're usually covered by different policies, and how each part of the loss is classified decides which policy pays for it.
Your homeowners or windstorm policy
- Roof, siding, soffit, windows and doors
- Rain driven in through storm-created openings
- Interior damage that follows wind damage
A separate flood policy (NFIP or private)
- Storm surge and rising water
- Water entering at ground level
- Building and contents, up to the flood policy's limits
When both hit, each policy can point at the other.
Picture a home where Isaias tore open the roof and surge then pushed water through the first floor. The wet ceilings, attic insulation and upstairs drywall came from above, through the wind opening. But once there's a water line on the walls, the whole interior can get written up as flood. The flood policy pays only for what the surge reached, and the ceilings, attic and upstairs rooms fall between the two policies, unpaid by either.
No flood policy? Then the wind damage is the part you're covered for, which makes it even more important that every bit of it is documented as wind.
- We document cause, not just damage. Water lines, wind openings, roof failures and the order things happened.
- We handle both claims together, so each policy is measured against the same full picture of the loss.
- We push back when damage is assigned to the wrong policy, so every covered dollar is paid under the right one.
Wind and flood damage at the same property?
Call (850) 600-4154Do These 3 Things First.
Protect your property. Protect your claim.
-
Document Before Cleanup
Photograph and video every damaged area before removing anything, whenever it's safe.
-
Prevent Additional Damage
Tarp openings or remove standing water if you safely can. Save every receipt, since reasonable emergency repair costs may be reimbursable under your policy.
-
Don't Assume the First Number Is Final
A first payment isn't always the full loss. If the carrier's scope looks short, it can be reviewed and supplemented.
Your Insurance Company Has an Adjuster.So Should You.
The difference is who they represent.
Have Questions About Your Claim?
Talk to a Public AdjusterFrom Storm Damage to a Documented Claim
-
WE INSPECT THE PROPERTY
A licensed Public Adjuster walks the whole property with you, inside and out, and records the damage before it's repaired or thrown away.
- Roof, siding, windows, doors, fences and other exterior damage
- Ceilings, walls, flooring, cabinets and damaged contents
- Moisture readings to find water behind walls and under floors
- Photos, measurements, drone aerials and a Matterport 3D scan where needed
-
WE BUILD THE CLAIM
We turn the inspection into a complete, documented claim, priced in the same software the carriers use.
- Policy review: coverages, deductibles, endorsements, and wind versus flood
- A line-item Xactimate estimate of the full repair scope
- Damaged contents and additional living expenses, if you're displaced
- Supporting photos, reports and the paperwork the carrier requires
-
WE HANDLE THE CARRIER
From then on, the insurance company deals with us. You get updates, not phone tag.
- All carrier communication, requests and deadlines
- We meet their adjuster at the property for re-inspections
- A line-by-line review of the carrier's estimate against ours
- Negotiation, supplements for missed or hidden damage, and appraisal where appropriate
Built to Document the Claim
- Drone ImagingFAA Part 107 aerial documentation where appropriate.
- Matterport 3DDetailed, measurable property documentation.
- Xactimate EstimatingLine-item property damage estimating.
- Licensed ContractorA Florida Certified Building Contractor on the team, for scope and code questions.
Real People. Real Florida Claim Experience.
Meet the VIP Team
No Recovery, No Public Adjuster Fee.
- Free initial claim review
- No upfront Public Adjuster fee
- Fee terms are disclosed in writing before you hire us
We've Been Here Before.
Hurricane Sally came ashore at Gulf Shores in September 2020 as a Category 2 storm and crawled across the Pensacola area. It moved so slowly that hours of wind and rain did as much damage as the peak gusts, and Pensacola Bay took on storm surge.
Our Public Adjusters mobilized to Northwest Florida right behind it. We worked claims from Perdido Key to Pensacola to Gulf Breeze: torn-off roofs, water through ceilings and walls, and claims that came back short or denied.
That came two years after Hurricane Michael, when our team was on the ground in Panama City the day after landfall. Our Panama City office has served the Panhandle ever since.
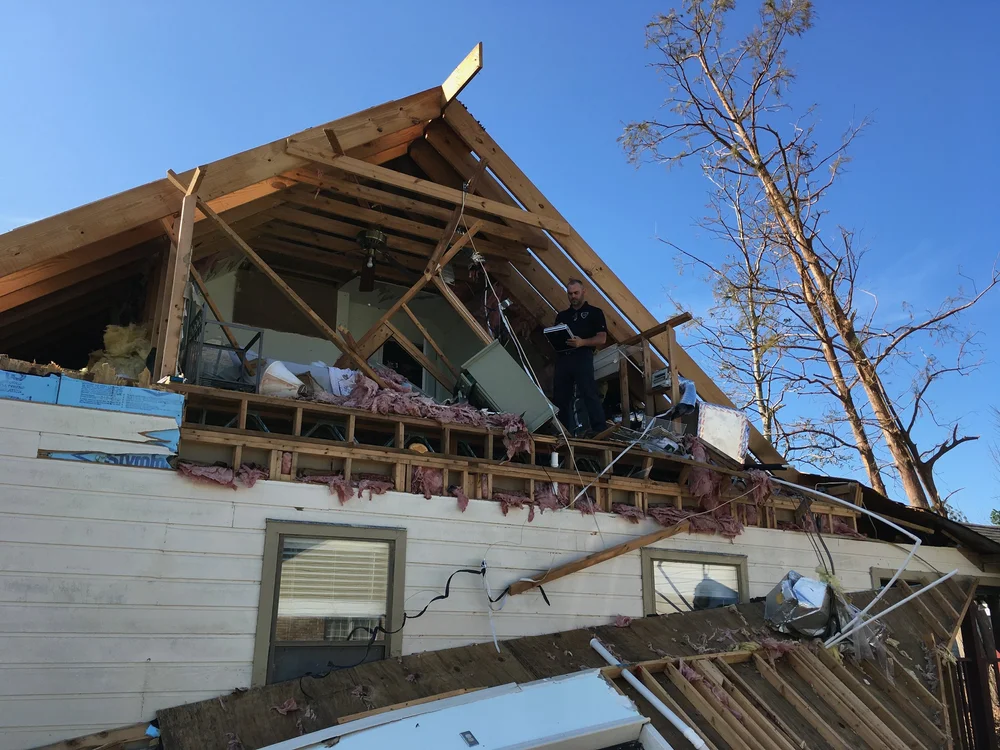
- 2018Hurricane Michael, Panama City
- 2020Hurricane Sally, Pensacola area
- 2026Hurricane Isaias. We're here now.
Gulf-front home with roof damage and wind-driven rain through the upper floor.
Roof covering torn off; water through ceilings, walls and flooring in several rooms.
Carrier initially denied the claim. We documented the wind damage and reopened it.
Amounts are approximate to protect client privacy. Results depend on each policy, the damage and the circumstances of the claim. Past results do not guarantee future outcomes.
We've Worked the Panhandle Before
From clients we represented after Hurricane Sally and Hurricane Michael.
"I hired VIP adjusting following hurricane Sally. Was very impressed they showed up with the correct instruments to do the job... Communication was awesome and very Timely."
"VIP Provided us excellent service after hurricane Sally. They were always willing to talk to us with any questions we may have and provided regular updates. Highly recommend!"
"I met Lance Petrie October 11th the day after Hurricane Michael in downtown Panama City, Fl... He took a lot of stress off of me when I signed up with him. I never had to call my insurance company."
"My home almost blew away during Hurricane Michael... VIP stepped in and took over the whole claim... I had never made a claim in my life and VIP held my hand through the entire process."
"My husband and I hired VIP Adjusting after Hurricane Michael. From day one we knew we were working with true professionals... They will be behind you every step of the way and will leave no stone unturned during the process."
Western Florida Panhandle
Close by when it counts.
Our Florida Panhandle team covers Pensacola and the beach communities from Perdido Key to Destin, working out of our Panama City office.
- An adjuster at your property, not just on the phone
- The same team from the first call to the final payment
- Answered 24/7 on our main line
Florida Panhandle Response Team
(850) 600-4154- Panama City Office
- 97 Oak Ave
Panama City, FL 32401 - Main Line
- 833-WITH-VIP
Before You Call
Do I need to file with my insurance company before calling you?
No. Call us before or after the claim is reported. If it isn't filed yet, we can help you file it, with the damage and your policy reviewed first so it starts on solid footing.
The insurance company already inspected or paid. Is it too late?
No. We can come on board at any stage of the claim, whether the carrier has already inspected, made a payment or denied it.
What does a Public Adjuster cost?
The initial review is free, and there's nothing up front. When a state of emergency is declared, Florida sets the cap on Public Adjuster fees at 10%, and that's what we charge on Isaias claims. Our fee comes only out of what's recovered. No recovery, no fee.
Do you handle flood and storm surge claims?
Yes, for property owners who carry flood coverage, including losses involving both wind and water.
Not Sure How Serious the Damage Is?
We'll take a look before you make decisions about the claim.
Main line, 24/7: 833-WITH-VIP